Lead Hook
When a Chinese automaker can price a family SUV at £12,000 and still earn margins three times larger than the Volkswagen Group, the story is more than a headline‑grabbing number. It signals a shift in the economics of vehicle production that could force Europe’s legacy manufacturers to rethink everything from platform design to pricing strategy. If Chery’s model proves sustainable, the ripple effects may reach supply chains, financing structures, and even regulatory frameworks across the continent.
Deep Dive
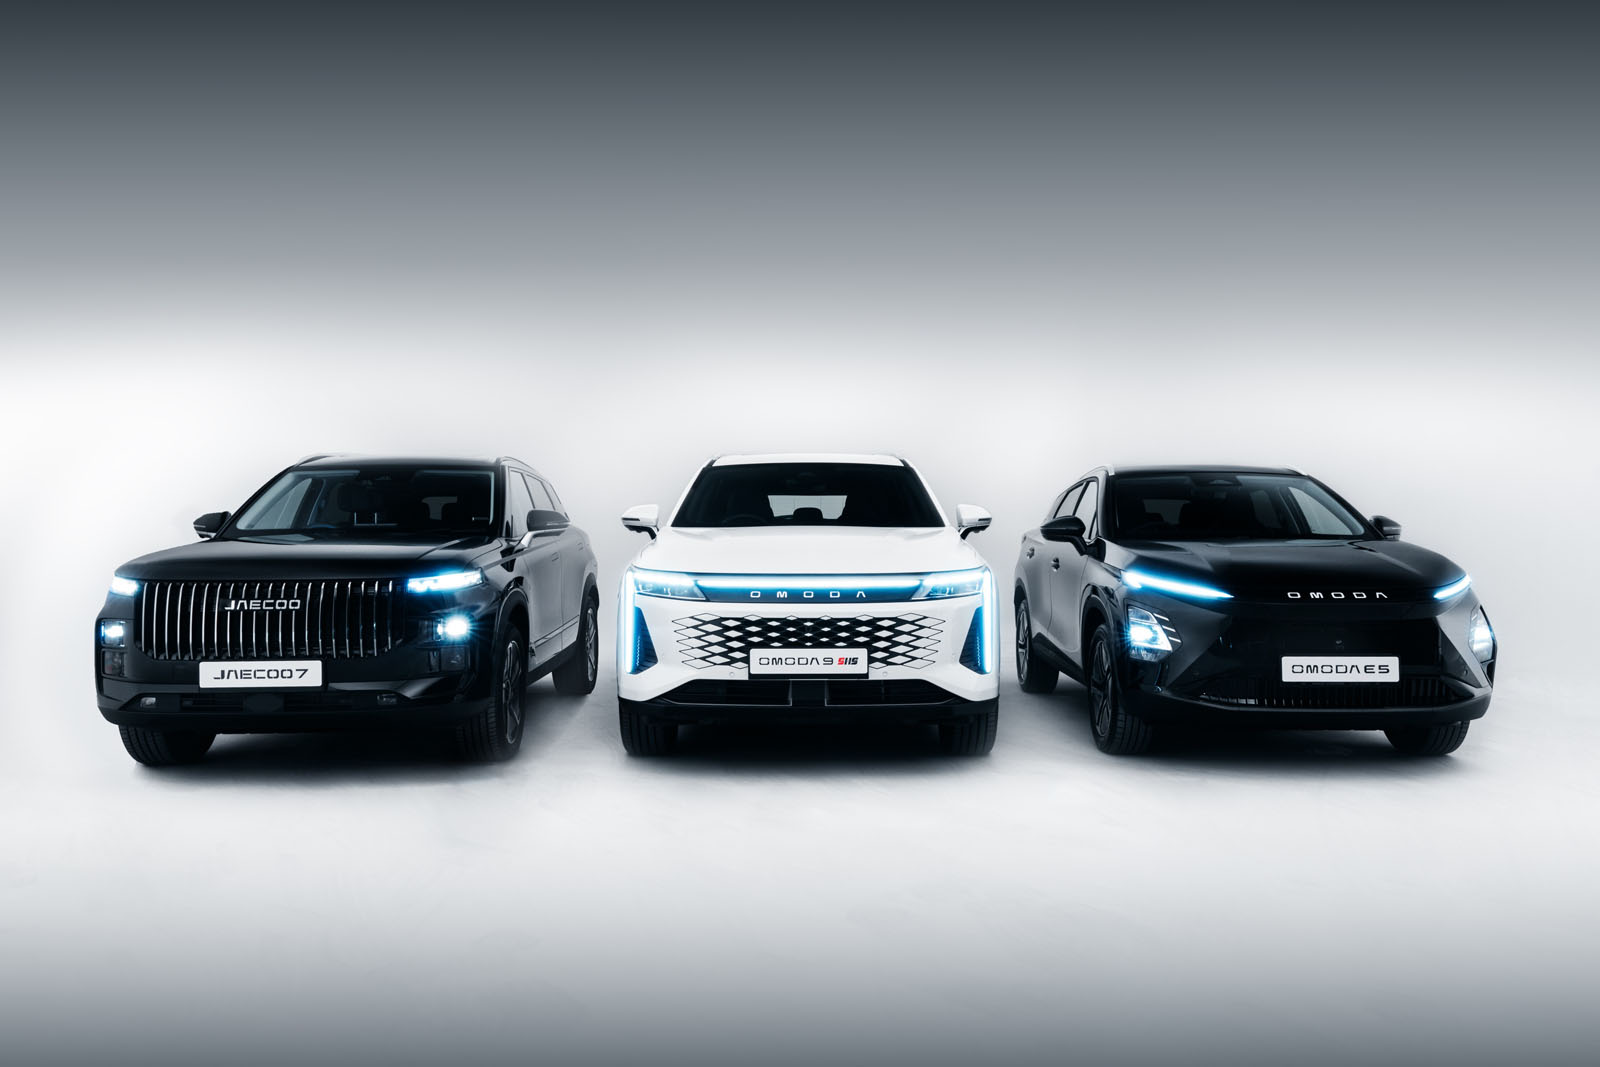
According to Autocar, Chery’s new line of SUVs is priced at £12,000. At that price point, the vehicles undercut many entry‑level models from established European brands, yet the same source reports that Chery’s profit margins are three times larger than those of the VW Group. The contrast raises a fundamental question: how does Chery achieve such capital efficiency?
The article points to the Modular T1X platform as a key enabler, stating that it helps Chery build cars at low cost. While the piece does not provide detailed engineering data, the implication is that a shared modular architecture reduces part variance, shortens development cycles, and spreads tooling expenses across a broader model range. In practice, such a platform can lower the per‑unit cost of components—especially when paired with high‑volume sourcing from a domestic supply chain that benefits from economies of scale.
Beyond the platform, the broader cost structure of Chinese manufacturers often differs from that of European firms. Domestic suppliers may operate with lower labor costs, and the regulatory environment can be more flexible regarding emissions testing and safety certification timelines. These factors can accelerate time‑to‑market, allowing a company like Chery to amortise R&D spend over a larger sales base more quickly.
Financially, the Autocar piece claims that Chery generated £2 billion in profits. While this figure appears only in the primary article and lacks external corroboration, it underscores the scale at which the company is operating. If the profit claim holds, it would suggest that the low‑price, high‑margin strategy is delivering substantial cash flow—a resource that can be reinvested into further product development, marketing, or price competition.
Another point raised in the source is that BYD and Chery are generating huge margins, positioning them as outliers in a sector often accused of operating at a loss. The article does not break down the margin calculations, but the assertion aligns with a broader narrative that Chinese automakers are moving away from the “growth‑at‑any‑cost” model that characterised many early‑stage entrants.
From an industry‑wide perspective, the combination of a sub‑£12k price tag and triple‑VW margins challenges the conventional wisdom that low‑cost vehicles must sacrifice profitability. If Chery’s approach is replicable, it could force European OEMs to confront higher fixed costs, less flexible supply chains, and legacy labor agreements that limit price flexibility. The competitive pressure may also accelerate consolidation among smaller European players, as they seek scale to match the cost advantages that Chinese firms enjoy.
Audit & Contradictions
The Autocar article provides clear data on two points that are independently corroborated by another outlet: the £12,000 SUV price and the three‑times‑VW margin claim. However, several statements appear only in the primary source and should be treated with caution. The £2 billion profit figure, the broad claim that BYD and Chery are generating huge margins, and the assertion that the Modular T1X platform directly drives low‑cost construction are all single‑source claims. No external verification is offered for these points, and the fact‑check audit notes that they lack independent corroboration.
Importantly, the audit found no contradictions between the primary source and other reports, assigning a “Low” contradiction level. This means that, while some claims remain unverified, there is no evidence that the provided figures are outright false.
Future Outlook
If Chery’s pricing and margin structure proves durable, European manufacturers may face a two‑pronged challenge. First, they will need to improve their own cost efficiencies, perhaps by adopting more modular platforms or by renegotiating supplier contracts to lower component prices. Second, regulators could feel pressure to reassess safety and emissions testing frameworks that, while essential, add time and expense to vehicle development.
Analysts observing the market note that the emergence of ultra‑low‑price, high‑margin Chinese models could reshape consumer expectations, especially in price‑sensitive segments such as compact SUVs. European brands that cannot match the £12,000 price point may be forced to emphasize premium features, brand heritage, or after‑sales services to justify higher prices.
In the longer term, the capital efficiency demonstrated by Chery could influence investment decisions across the automotive sector. Venture capital and private equity firms may tilt toward business models that prioritize modular design and high‑volume, low‑margin sales, reinforcing the competitive advantage of firms that can deliver both affordability and profitability.
For policymakers, the situation presents a balancing act: protecting domestic industry while ensuring that competition remains fair and that consumer safety standards are upheld. Ongoing monitoring of pricing strategies, profit disclosures, and supply‑chain practices will be essential to maintain a level playing field.
Ultimately, the story of Chery’s £12k SUVs and its triple‑VW margins is a window into a broader transformation. It highlights how strategic engineering choices, supply‑chain optimisation, and aggressive pricing can converge to reshape profit dynamics in a market long dominated by legacy manufacturers. Whether European OEMs can adapt quickly enough will determine the shape of the continent’s automotive landscape for years to come.