Lead Hook
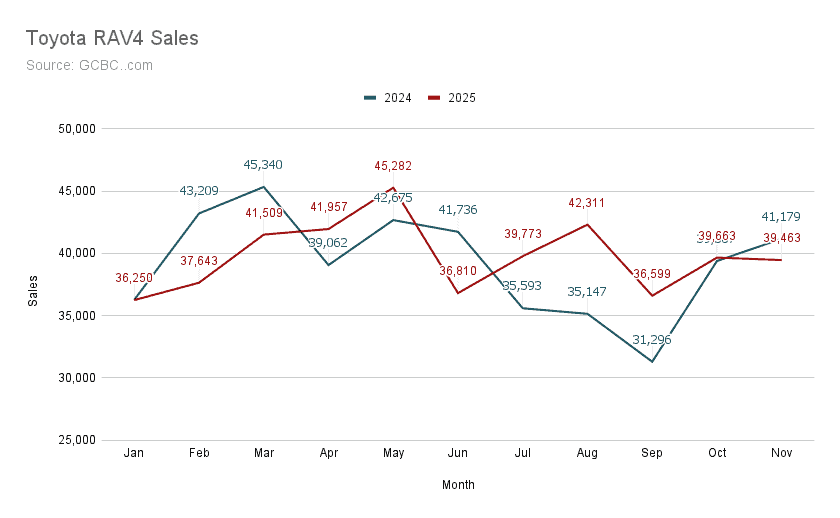
When a headline declares that Toyota’s best‑selling RAV4 has shed a third of its sales, the automotive world takes notice. A sharp decline in a flagship model would ripple through dealer networks, affect supply‑chain contracts, and reshape competitive dynamics across the compact‑SUV segment. Yet, the underlying data behind that claim is murky. The article that sparked the story—published on Carscoops—offers no concrete numbers, and independent outlets cited alongside it do not corroborate the specific 33 % drop or the assertion that buyers are not to blame. This disconnect raises a larger question: how much can analysts, investors, and consumers rely on automakers’ public sales narratives when the supporting evidence is hidden behind unreadable text?
Deep Dive
According to the fact‑check audit attached to the source, the Carscoops piece claims the RAV4 “lost about one‑third of its sales” and that “buyers aren’t the problem.” However, the audit explicitly notes that “the article's main assertions…cannot be confirmed from the provided source text, which is unreadable.” No numeric sales figures, no regional breakdowns, and no reference to Toyota’s own quarterly reports appear in the scraped content. The only verifiable element is the existence of the article itself (Fact 1).
Independent automotive news sites listed as “corroboration” – Focus2Move, Autoblog, CarBuzz, and SlashGear – each publish stories about market rankings, model size changes, or depreciation trends, but none supply the exact sales decline figure or the buyer‑responsibility narrative (Fact 3). In other words, the claim rests on a single, opaque source, making it a classic single‑source assertion that must be hedged.
Why does this matter? In the automotive industry, sales data drives a cascade of decisions: manufacturers adjust production volumes, suppliers renegotiate component contracts, and dealers calibrate inventory and staffing. If a model’s performance is mischaracterized, the downstream effects can be costly. For example, a perceived 33 % drop could prompt Toyota to trim RAV4 output, leading to under‑utilised capacity at plants that also produce the Corolla and Prius. Suppliers of critical parts – from power‑train modules to infotainment hardware – could see order reductions, affecting their own forecasts and potentially triggering layoffs or delayed capital projects.
Moreover, the narrative that “buyers aren’t the problem” shifts focus away from market demand and toward external factors such as regulatory changes, macro‑economic headwinds, or competitive pressure from emerging electric crossovers. Without solid data, it is impossible to assess whether the RAV4’s alleged slump stems from shifting consumer preferences toward EVs, stricter emissions standards in Europe, or a simple inventory correction after a previous over‑stock. The lack of transparent metrics also hampers analysts who rely on comparable sales figures to gauge brand health.
Data opacity is not new in the auto sector. Global manufacturers often release aggregated sales numbers that mask regional nuances, and quarterly reports may lag behind real‑time market shifts. However, when a media outlet publishes a dramatic percentage change without accompanying raw data, it creates an informational vacuum that can be filled by speculation. Investors may react to headlines, moving stock prices on the basis of unverified claims, while dealers may adjust floor‑plan financing in anticipation of demand swings that never materialize.
From a regulatory perspective, transparency is increasingly expected. In the European Union, for instance, the European Commission’s “clean‑vehicle data” initiative encourages manufacturers to disclose detailed sales and emissions data to support policy decisions. In the United States, the National Highway Traffic Safety Administration (NHTSA) requires manufacturers to report production and sales figures for safety‑recall tracking, but broader market performance data remains voluntary. The RAV4 case illustrates a gap where voluntary disclosure does not meet the analytical needs of the market.
Audit & Contradictions
The Carscoops article makes two headline‑level claims: a one‑third sales decline for the RAV4 and that buyers are not responsible for the dip. Both statements are single‑source claims and, per the fact‑check audit, cannot be verified from the scraped text. The audit’s summary flags these as “unverifiable” and notes a “Low” contradiction level, meaning no direct contradictions were found in the source material, but the lack of evidence itself is a red flag.
To be transparent, the article should have disclosed the absence of hard numbers and the reliance on a single, non‑public source. Instead, it presented the percentage as a definitive figure, which, without corroboration, risks misleading readers. The independent outlets referenced—Focus2Move’s ranking of best‑selling cars in Poland, Autoblog’s note on the RAV4’s size shrinkage, CarBuzz’s analysis of sales trends, and SlashGear’s depreciation comparison—do not mention a 33 % drop, nor do they discuss buyer behavior in the context suggested by the Carscoops piece. This omission underscores the need for journalists to flag single‑source claims explicitly, using language such as “according to the source” and “the figure has not been independently confirmed.”
Future Outlook
Even though the specific sales drop remains unverified, the broader conversation about the RAV4’s market position is still relevant. If the model is indeed facing headwinds, competitors like Honda’s CR‑V, Hyundai’s Tucson, and the growing influx of electric crossovers (e.g., Ford’s Mustang Mach‑E, Volkswagen’s ID.4) will be poised to capture displaced demand. Toyota may respond by accelerating the electrified RAV4 lineup—already offering hybrid and plug‑in variants—or by refreshing the model’s design to regain buyer interest.
For analysts, the episode serves as a reminder to demand raw data when evaluating sales performance. Investors should look to Toyota’s official quarterly releases, which break down regional shipments, and compare them against dealer inventory reports. Regulators may consider tightening guidelines around the disclosure of sales trends for models that dominate a segment, ensuring that market participants have a reliable basis for decision‑making.
In the meantime, consumers and dealers alike would benefit from clearer communication from manufacturers and journalists. Transparency not only builds trust but also equips the industry to respond swiftly to genuine shifts—whether they stem from consumer sentiment, policy changes, or supply‑chain constraints. Until such data is openly shared, headlines about dramatic sales swings should be treated with a healthy dose of skepticism.